Insight Partners Veteran Devin Parekh Unpacks AI Valuations, Liquidity Pressures, and the Evolution of Global Venture Capital

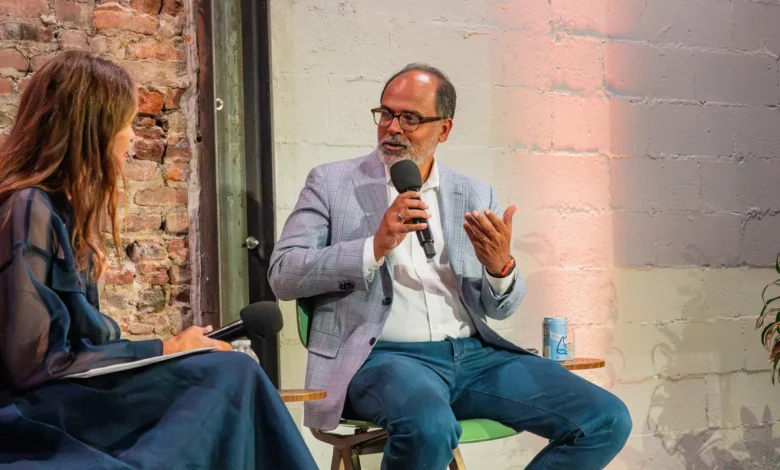
In the rapidly evolving landscape of venture capital, few leaders command the tenure and perspective of Devin Parekh. Having co-managed the heavyweight investment firm Insight Partners for 26 years, Parekh has navigated multiple market cycles, technological revolutions, and macroeconomic shifts. Unlike many high-profile venture capitalists who maintain a constant, vocal presence across social media platforms and industry podcasts, Parekh and Insight Partners have historically maintained a lower public profile, preferring to let the firm’s vast portfolio dictate its reputation.
Speaking candidly during a sit-down interview with TechCrunch at the StrictlyVC event in New York City, Parekh offered a rare, unvarnished look into the inner workings of a $90 billion assets-under-management (AUM) behemoth. Throughout the discussion, he addressed some of Insight’s major wins—including early and sustained bets on data analytics leader Databricks and stakes in frontier artificial intelligence giants OpenAI and Anthropic—alongside notable losses, such as missing out on buzzy European AI legal-tech startup Legora to rival firm General Catalyst. Furthermore, Parekh weighed in on the intensifying debate surrounding artificial intelligence risk, the complex conflicts of interest inherent in modern venture investing, and the enduring rationale behind maintaining a diversified portfolio strategy despite the industry-wide stampede into frontier AI labs.
Main Facts and Strategic Positioning
Insight Partners operates as a global scale-up software investor, managing approximately $90 billion in AUM. Despite its massive financial footprint, the firm deliberately resists the urge to pontificate on macroeconomics or geopolitical events—a tendency Parekh gently critiqued among peers during the recent New York gathering.
"Every venture capitalist thinks they’re an expert on everything now—epidemiology during COVID, geopolitics during the war," Parekh remarked. "Our attitude has been: Let the portfolio do the talking. We’re investing in founders and companies. We have to communicate enough that people know who we are, but our performance should speak for itself."
This philosophy underpins Insight’s flexible investment strategy. Rather than adhering to fixed geographic allocations or rigid stage quotas, the firm evaluates opportunities temporally. Its exposure across early-stage venture, growth equity, and buyouts fluctuates dynamically from fund to fund. However, market realities have shifted these levers. Parekh noted that the buyout market remains sluggish due to elevated interest rates, debt markets that are currently unreceptive to software transactions, and compressed exit multiples. Consequently, Insight has not executed a major buyout deal since 2024.
On the venture front, however, the firm is navigating a familiar yet concerning landscape. Parekh drew direct parallels between the current pace of rising valuations and the hyper-inflated market of 2021—a cycle that ultimately yielded painful corrections. In a healthy market, a follow-up funding round is justified by incoming data, allowing investors to pay a higher price in exchange for reduced risk. In the current climate, however, rounds materialize so rapidly that incremental data is virtually nonexistent. Investors are paying premium prices without mitigating risk.
Insight’s strategic countermeasure has been to lean further into early-stage investments. Armed with a scale fund, the firm can deploy smaller initial checks—typically $20 million to $25 million rather than hundreds of millions—and subsequently double down on proven winners. This methodology powered significant returns in cybersecurity standout Wiz, where Insight participated in the Series A round and systematically increased its position across subsequent financings, compounding its gains while containing downside exposure.
Chronology and the Evolution of Global Talent and Dealmaking
The globalization of technology talent has fundamentally altered how venture firms source deals. Talent is no longer exclusively tethered to Silicon Valley. Illustrating this shift, Insight’s leadership actively competed for European legal-tech startup Legora, with partner Jeff Horing flying directly to Stockholm to pitch the founder. Ultimately, Insight lost the deal to General Catalyst—an outcome Parekh accepted with pragmatic equanimity, noting that in a vast global market, firms do not need to win every competitive situation.
Nevertheless, geographic nuance persists within specific technology verticals. While pure AI infrastructure talent remains heavily concentrated in San Francisco—prompting a new generation of investors, including Parekh’s 23-year-old son, to relocate to the Bay Area—verticalized applications tell a different story. Financial technology applications, such as Ramp, draw heavily from New York’s dense financial services talent pool, proving that vertical AI investing offers broader geographic diversity than foundational infrastructure.
The timeline of technological adoption also dictates Insight’s patience with emerging sectors. Physical intelligence and robotics, for instance, remain largely in experimental stages. While acknowledging their eventual commercial viability, Parekh views current robotics investments as science projects requiring speculative bets on the exact timing of market adoption. While younger investors view physical AI as a mandatory frontier, Insight maintains a measured, observational stance.
Supporting Data, Portfolio Construction, and the Artificial Intelligence Concentration
The concentration of venture capital dollars within a handful of frontier AI labs has dominated industry discourse. According to recent market data, OpenAI and Anthropic commanded roughly half of all venture capital deployment during the first half of the year. This dynamic has sparked intense debate among limited partners (LPs) regarding concentration risk.
Insight has avoided overexposure to single-asset concentration, maintaining a diversified portfolio across its 13 flagship funds. Parekh highlighted that while some competing funds are raising entire vehicles predicated on allocating 35% to 40% of their capital into just one or two frontier AI companies, historical data over long investment horizons consistently rewards diversification.
Yet, managing stakes in direct competitors—specifically holding positions in both OpenAI and Anthropic—once represented a strict taboo within venture capital. Parekh explained that internal debates at Insight focused less on ethical or strategic conflicts and more on stage-dependency. Early-stage investors driving board governance cannot easily back competing foundational models. However, at later stages, without board seats or governance responsibilities, institutional investors essentially act as buyers of valuable public or private stock.
Insight categorized OpenAI as the dominant consumer play and Anthropic as a clear enterprise strategy, though those distinctions continue to blur. As these foundational labs demand capital infusions ranging from $30 billion to $100 billion, they have outgrown the ability of single investors to dictate exclusivity. Consequently, information-sharing restrictions and strict governance boundaries are maintained at early investment stages, even if modern founders exhibit heightened sensitivity to minimal revenue overlaps.
Liquidity, DPI, and the Secondary Market Imperative
A central tension in the current private markets ecosystem revolves around liquidity. Following the massive capital fundraising waves between 2021 and 2023, numerous venture funds accumulated substantial capital without returning meaningful liquidity to their limited partners. Parekh issued a stark warning regarding the fate of first- and second-time fund managers who fail to prioritize distributions-to-paid-in (DPI) capital.
"LPs want to know you can turn positions into cash; that’s the job," Parekh stated.
Reflecting on Insight’s own evolution, Parekh admitted that the firm was previously guilty of holding onto winning positions indefinitely under the assumption that valuations would perpetually double. However, LPs measure success in realized liquidity. Over the preceding two years, Insight returned more than $20 billion to its limited partners through strategic secondary sales and initial public offerings, with additional billions pending.
The secondary market has thus transformed from a peripheral mechanism into an essential liquidity valve. Founders facing frothy, highly compressed valuation windows are increasingly encouraged by institutional backers to de-risk by taking secondary liquidity off the table. Parekh frequently advises founders receiving inflated valuation offers to consider de-risking 10% to 20% of their holdings against inevitable macroeconomic corrections. Compounding multi-billion-dollar valuations at unsustainable growth rates defies long-term mathematical reality, making timely de-risking a prudent fiduciary safeguard.
Broader Impact, Public Market Implications, and Future Outlook
As the venture capital ecosystem prepares for an anticipated wave of mega-cap initial public offerings—with companies like Anthropic, OpenAI, and SpaceX approaching public market readiness—the broader implications for institutional investors and tech startups are profound. Anthropic, achieving unprecedented scale within four years of inception, exemplifies the hyper-acceleration characteristic of modern enterprise software.
The impending public debut of these trillion-dollar-adjacent entities will test public market absorption capacity. While public market investors accustomed to astronomical private growth trajectories must adjust to normalizing corporate maturation curves, the broader pipeline of venture-backed companies depends on these IPO windows opening successfully over the next 12 to 18 months.
Ultimately, the cyclical nature of venture capital remains stubbornly resilient. LPs frequently oscillate between risk aversion and aggressive capital deployment, mirroring broader human behavior in financial markets. For seasoned firms like Insight Partners, navigating these oscillations requires adhering to rigorous portfolio reviews—such as analyzing hundreds of portfolio companies over multi-day evaluations—to identify inflection points, optimize capital allocation, and uncover hidden opportunities like the firm’s successful historic acquisition and eventual exit of security platform Armis. As the industry confronts macroeconomic headwinds and AI-driven transformation, Parekh’s disciplined emphasis on liquidity, diversification, and operational execution serves as a defining blueprint for institutional scale.
Related posts: